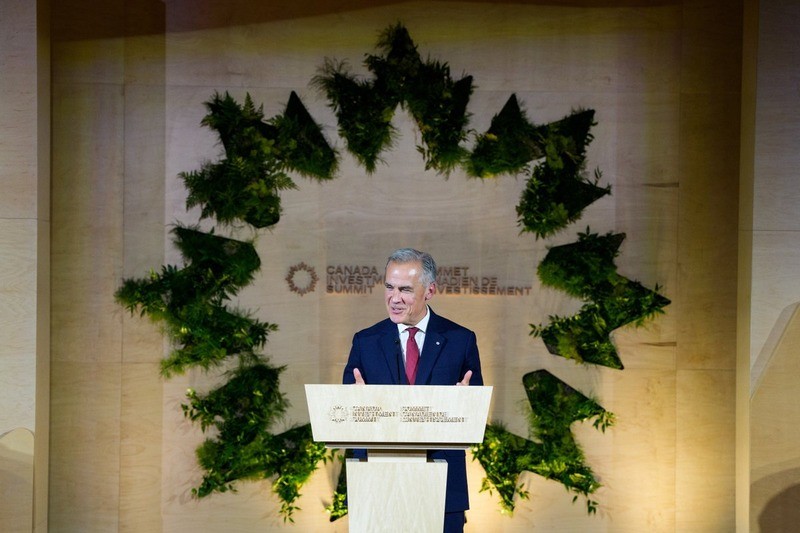
The measure was announced at the first Canada Investment Summit in Toronto on September 15 as the government seeks to catalyse more than $1 trillion in total investment over five years through public, private and institutional partnerships.
The new incentive expands the scope of assets eligible for immediate deductions from roughly 15% to more than 65%, covering investments including fibre-optic cable, mining property, oil and gas pipelines, software, research and development, computer equipment, aircraft, vehicles, patents, rail track, bridges and roads.
The government said the measure, combined with making immediate expensing permanent, will reduce the marginal effective tax rate on new business investment in Canada from roughly 13% to 6.4%.
Tax changes target wider range of investments
The Productivity Mega Deduction builds on the Productivity Super-Deduction introduced in Budget 2025, which allowed businesses to immediately deduct 100% of the cost of eligible new investments in machinery, equipment and technology.
The government said the expanded measure will allow businesses to recover investment costs sooner and is intended to encourage greater capital investment across the country.
Prime Minister Carney said the changes were designed to strengthen Canada’s position as a destination for new investment.
"Canada has what the world wants. We’re an energy superpower with the most educated workforce in the world and rock-solid fiscal strength," Carney said.
"We are capitalising on these strengths and making Canada the best place in the world to invest," he added.
Part of broader investment push
The announcement came as the Canada Investment Summit brought together investors from nearly 30 countries managing more than $100 trillion in assets.
The government said the summit generated nearly $500 billion in new investment commitments, including commitments from Canadian pension funds, insurers, institutional investors and major banks.
Finance Minister François-Philippe Champagne described the Productivity Mega Deduction as a major change to Canada's business tax system.
"With the Productivity Mega Deduction, we are reinforcing Canada’s position as the most competitive country in the G7 for new business investment and setting the conditions for an investment supercycle," Champagne said.
The government said its capital investments and incentives, totalling about $280 billion over five years, are expected to enable more than $1 trillion in total investment from public, private and institutional partners.
The latest tax changes form part of the government's broader effort to increase capital investment and position Canada as a competitive destination for businesses seeking to expand and build new infrastructure.